Arab dreams are shattered

The hole in Saudi Arabia’s budget caused by America’s war against Iran is forcing the rulers in Riyadh – blinded by the money from the oil business – to give up their dreams.

Incredible megacities were to be built – the city known as ‘The Line’ was to be 170 km long, and futuristic places such as ‘Neom’ or ‘New Murraba’ were to act as magnets for tourists and investors who would benefit from the shift from an oil-based to a service-based economy. Now, by 2030, only 5 kilometres of the 170-kilometre megacity will be built, and other projects have also been scrapped. Why?

It is clear that less oil has been and is being transported through the Strait of Hormuz. It is also well known that the Iranians retaliated by attacking the Saudis: the onshore transport infrastructure became the target of military attacks by Iranian drones, which damaged pumping stations along the east-west pipeline, whilst the attacks on the SABIC petrochemical complex in Al-Jubail caused fires and temporary shutdowns of the facilities.

However, another, even more important factor is the United Arab Emirates’ withdrawal from OPEC. Whilst Saudi Arabia requires an oil price of $86.60–$96.20 per barrel to offset its enormous expenditure and investment (the so-called fiscal breakeven oil price), the UAE already achieves a financial balance at around $50 per barrel. Abu Dhabi has therefore recognised that artificially reducing its own production to rescue the Saudi budget is a move that runs counter to its national interests, and has left OPEC.

For Riyadh, the consequences of this bold move by the UAE are proving to be severe. The OPEC+ framework, now abandoned by the Emirates, has lost its ability to manage oil prices effectively. In the past, Saudi Arabia was able to act as a sort of supply buffer and reduce its own production to raise prices on the markets. Under the current circumstances, any unilateral reduction in production by Saudi Arabia results in ADNOC and non-cartel producers such as the US, Guyana or Brazil immediately gaining market share, without any noticeable price increases. Riyadh therefore finds itself in a situation where a reduction in output would dramatically erode its revenues, whilst an increase in production would drive the oil price down to $60 or below, exacerbating the Kingdom’s financial collapse.

The geopolitical situation in the Gulf is causing a rift between Washington and Riyadh: the Saudi authorities refused to make their air bases and airspace available to the Americans to carry out ‘Project Freedom’, an operation designed to protect supertankers. Saudi strategists have recognised that the military escalation of the conflict with Tehran is causing ever-greater damage to infrastructure and increasingly paralysing the economy. They also recalled that the US military could leave the region at any time, whilst Iran will remain a permanent neighbour.

At the same time, Riyadh slowly began to forge new alliances. In May 2026, Saudi Arabia struck a deal with Pakistan under which Islamabad deployed 8,000 troops, a squadron of fighter aircraft and air defence systems to the Kingdom. This move not only strengthened the protection of Saudi oil facilities but also made Pakistan a mediator in relations between Riyadh, Washington and Tehran.

There is, after all, life beyond the oil fields: the economy outside the oil industry is growing at an astonishing rate and already accounts for 55.4 per cent of the Kingdom’s gross domestic product. The tourism sector set a historic record in 2025: total tourist spending reached 304 billion rials (81.1 billion dollars). This figure was generated by 123 million visitors. It might be worth investing in religion (places such as Mecca) rather than in science-fiction visions. 
Peace is an illusion

Negotiations took place between the US and Iran in June. These resulted in the announcement of a temporary agreement (Memorandum of Understanding) providing for a 60-day ceasefire and the reopening of the Strait of Hormuz to tankers. Both sides have portrayed this as a step towards genuine peace. But can we really believe that?

The latest statement by US Vice-President J. D. Vance casts doubt on this. In an interview with Michael Knowles, Vance explicitly admitted that this was in fact a tactical pause and not a permanent agreement. He explained that the main objective was to restore global oil reserves, and that what happens next remains an open question. War could break out again, or there could be lasting peace. The latter, however, depends on a “major shift in Iran’s approach”.

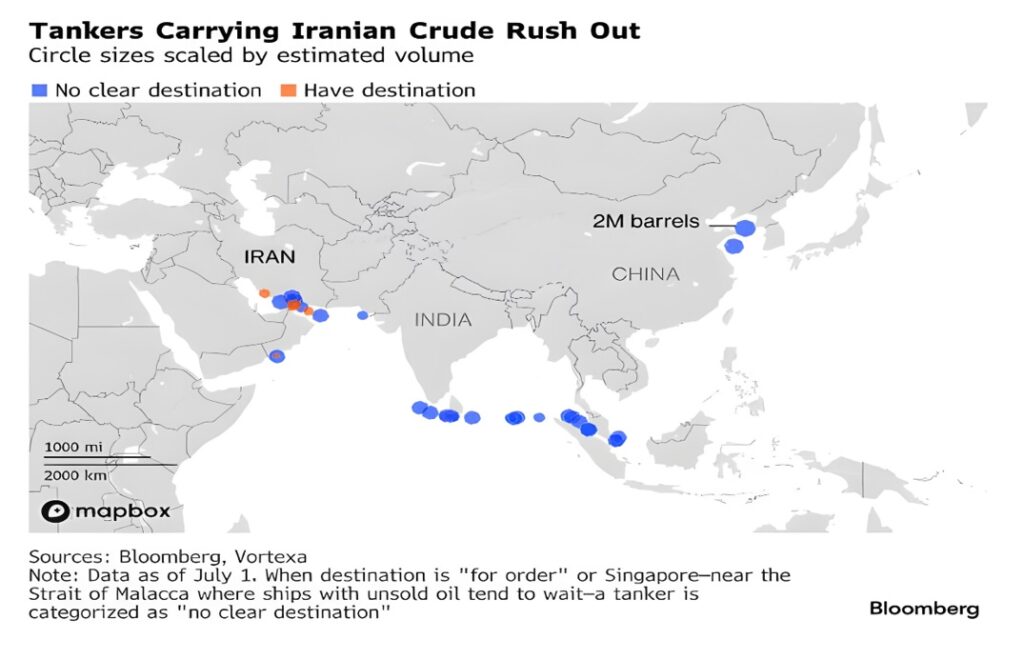
Apart from Vance, it is safe to assume that Tehran will not back down from its demands, and therefore an escalation is highly likely. However, there is one factor that could really weaken Iran’s position: oil. Iran is having serious problems selling it. Following the announcement of the MOU and the lifting of some of the sanctions, Tehran has attempted to export oil on a massive scale, but so far without success. According to Stephen Innes, between late June and early July, more than 58 million barrels of Iranian oil were at sea, of which more than 90 per cent had no clear destination, as shown in the chart below.

Fully loaded tankers are anchored near the Strait of Malacca and the Chinese coast. Iranian oil is flowing there in huge quantities (more than 2 million barrels), but Chinese refineries are unwilling to buy it. The reason is the sharp fall in domestic demand in China, which is leaving Chinese refineries with insufficient margins.  In any case, Iran only has until the end of August before the period set out in the MOU expires. The longer the problems with oil sales persist, the greater the pressure on Tehran’s public finances, as the anchored tankers merely incur additional costs. This, in turn, could lead to Tehran making major concessions to the US when the time comes for further negotiations.

At the same time, we must not forget Israel, which will do everything in its power to torpedo the peace negotiations. The current agreement should therefore be viewed primarily as a strategic pause before the cards are reshuffled in the Middle East conflict.


Spirit is running low

 The fuel shortage is becoming increasingly serious. Lufthansa has already cancelled 20,000 flights. Air France has increased prices for economy class tickets by 50 euros per return journey, and the Dutch airline KLM has suspended more than 160 flights. At the same time, the International Energy Agency has announced that Europe will only have enough aircraft fuel reserves to last six weeks. However, the problem is already affecting industries across the globe. All major airlines are currently making massive cuts, particularly Turkish Airlines, which has cancelled nearly 20 routes. There are already companies that simply haven’t been able to cope with the situation. One such company is the US carrier Spirit Airlines, which filed for bankruptcy a few days ago. Although the name of this carrier may mean little to many readers, it is worth looking at the figures. Last year, the company operated more than 300,000 flights, carried 30 million passengers and held a 3.5% market share among US airlines. It is therefore not a small airline, but a national giant with more than 17,000 employees.

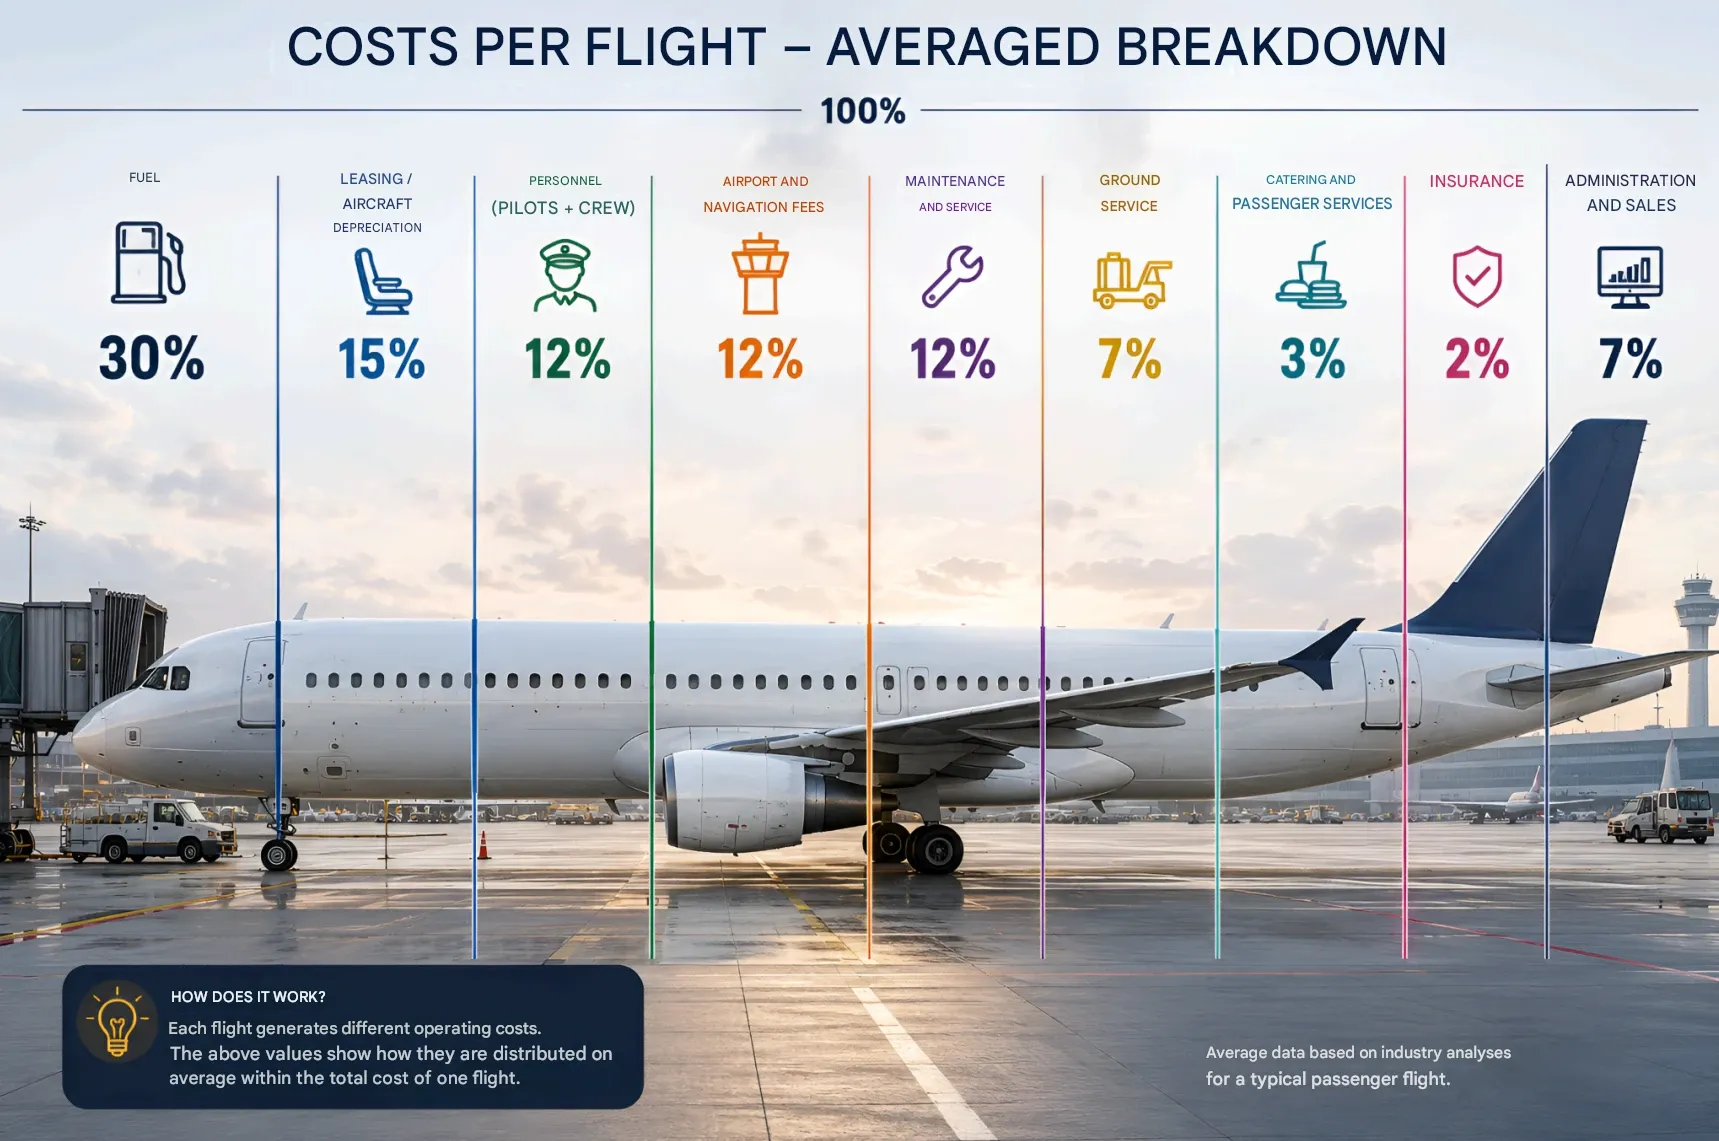
If we break down the cost of a typical passenger flight into its main categories, we can see that airlines are heavily dependent on the price of aviation fuel. On average, this accounts for 30% of the total cost.

And that is why Europe finds itself in a particularly difficult situation. This is because up to 70% of the crude oil that is subsequently processed into Jet A-1 aviation fuel comes from the Gulf region. This primarily includes Kuwait and Saudi Arabia, as well as the United Arab Emirates and Qatar. This makes the situation very dangerous, as any further blockade of the Strait of Hormuz will exacerbate these problems on a daily basis. Furthermore, it should be remembered that the availability of aviation fuel affects not only passenger traffic but also freight transport, which in practice is the first to feel the impact of disruptions. This is because, unlike passenger transport, where part of the costs can be passed on to customers gradually, any change in fuel prices for cargo is almost immediately reflected in the freight rates for every kilogram of cargo.

So here’s a handy tip: if you’re planning to fly on holiday, book a package with a price guarantee, as travel agencies such as TUI or DERTOUR are entitled to charge us a so-called fuel surcharge. These are additional costs, in accordance with the rules, which they can impose on the customer 20 days before departure if travel costs rise significantly.

The paradoxes of green energy

Energy is a commodity traded on the markets. This happens every day, at every moment. If the price of electricity falls, the electricity producer stops feeding his electricity into the grid. However, producers usually have no choice, as wind turbines keep turning and solar panels operate automatically. Energy storage systems are expensive and currently have barely enough capacity to store surplus electricity for hours or days when demand is high.

The more photovoltaic cells feed into the grid, the more frequently this problem arises: too much energy is generated precisely when everyone is producing the most. On sunny days, particularly at midday, there is more electricity than the system can consume. The more the sun shines, the more electricity flows into the grid at the same time – and the more frequently the price drops to zero or below. In extreme cases, the energy producer has to pay extra just to get someone to take the electricity off their hands. The following chart shows how the percentage of hours with negative electricity prices is rising in Europe and individual regions – and in which countries the biggest increases were recorded in 2025.

A negative electricity price is not a gift to the recipient. It is a signal that the system has been ‘overwhelmed’ by the surplus. Photovoltaic operators therefore sell electricity at a lower price relative to the average market value, which is not reflected in the final price paid by the end consumer. Why? Because there are too few energy storage operators willing to buy the electricity for free or at a premium and sell it at peak prices in the evening. Whilst the number of electricity storage facilities is rising steadily, the electricity grid is not being expanded to keep pace with the rapid growth of solar, wind and storage. As a result, on sunny days, photovoltaic plants and wind farms are being shut down more frequently because it is not possible to absorb the electricity. According to reports, 8.5% of onshore wind production was curtailed in the United Kingdom in 2024. In Germany, wind curtailment (onshore and offshore) has been above 5% since 2022, and solar curtailment rose to 2% in 2024. In China, this rose to 4.1% for wind and 3.2% for solar energy in 2024; preliminary figures for 2025 suggest over 5% for both, according to the IEA.

A modern 100-megawatt storage facility requires around 0.5 to 1 hectare of land. How much farmland would be needed for the massive offshore projects involving terawatt-scale wind farms currently being built in the Baltic Sea (for example, in Poland)? How much lithium and other metals – mined in the developing world in ways that are far from environmentally friendly – are required for these large battery energy storage systems (BESS)? Is that sustainable? Really?

I don’t think so. But it is politically correct, because it creates the illusion that we are becoming less dependent on fossil (read: Russian, Putin-controlled) raw materials.


Why must raw materials become more expensive?

Gold

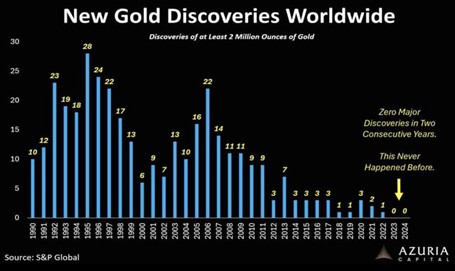
For a gold mine to be profitable, the deposit must contain at least 2 million ounces of the precious metal, as this is the only way to ensure production for many years to come. In previous years/decades, new deposits were discovered and supply was guaranteed. However, in the last two years of the gold rush, when gold was being sought everywhere, no major deposits were discovered anywhere in the world! This is the first time in history and, of course, an argument for a further rise in price.

Petroleum

Shale oil is running out in the United States. According to the latest data from the Energy Information Administration (EIA), shale oil production will gradually decline, mainly due to the depletion of deposits. The Permian Basin, one of the largest and most important shale basins in the world, is expected to produce less and less shale oil in the coming years. The impending supply deficit and the ever-increasing demand for this raw material are prompting leading oil producers to seek alternative sources for extracting black gold, especially in offshore deposits. Perhaps this is also the reason for the possible war against Iran, in order to secure reserves there, as in Venezuela.

Metals and rare earths

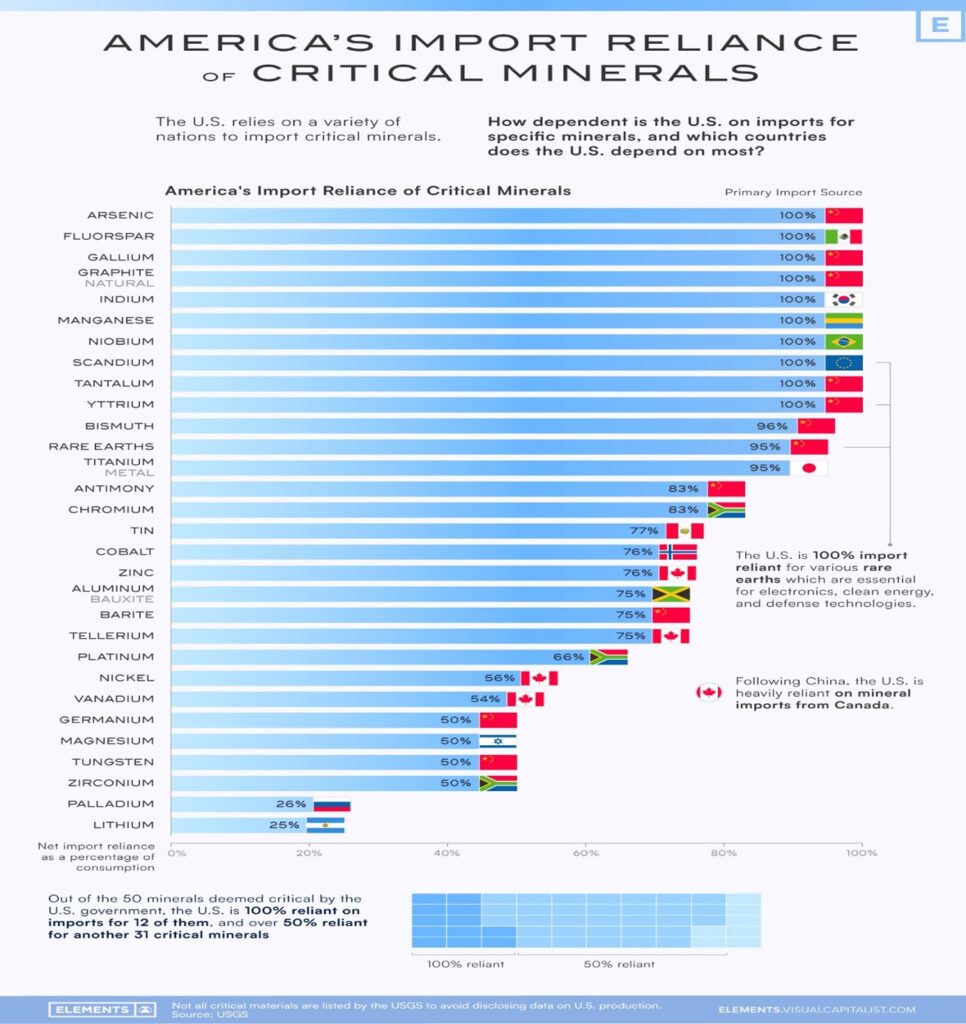
When it comes to both, the West is completely dependent on China and Africa. The following graph shows how heavily the US depends on other countries when it comes to minerals:

Source: Elements

Particular attention should be paid to rare earths, a group of 17 nearly indistinguishable heavy metals with similar properties that are indispensable in a wide variety of technologies, high-performance magnets, electronics and industry as a whole, as well as natural graphite, which is found in lithium-ion batteries. When Trump imposed tariffs on China, Beijing responded with restrictions on rare earth exports, which only exacerbated the geopolitical situation surrounding these materials.

The data shows that Africa’s share of resources and production of important raw materials is as follows:

  • Platinum: 90% of global resources (mainly South Africa and Zimbabwe). Platinum is needed in catalytic converters and hydrogen technologies.
  • Cobalt: 70-75% of global production comes from the Democratic Republic of Congo. It is one of the key components of lithium-ion batteries.
  • Chromium: 85% of global reserves are of high quality. Required for the production of stainless steel.
  • Manganese: 80% of global resources (mainly South Africa). Key to the production of steel and batteries.
  • Tantalum: 60-70% of global resources (DRC, Rwanda). Indispensable in every smartphone and laptop (capacitors).
  • Gold: approx. 40% of global resources.

At the same time, Africa remains the least geologically explored continent on Earth. Canada spends more than US$2 billion annually on field exploration, while all African countries combined spend just over US$1 billion. This shows that if the African continent were not so politically unstable, many more deposits would likely be discovered there. In addition, more and more mines are being controlled by the Chinese (e.g. the cobalt mines in Congo), which poses a real threat to the West. 

The energy crisis is planned and desired Electricity prices skyrocket, but that’s our new better world after all

The Emissions Trading Systems (ETS) were introduced with the Kyoto Protocol and imposed on the EU and other countries by the infamous Al Gore. His idea that whoever produces more CO2 has to pay for it was seemingly clear at the beginning and many immediately embraced it, but the ETS quickly became financial instruments in the hands of large investors and thus began to serve as such for speculation. ETS became a commodity on the stock exchange, traded just like bitcoin or CFDs (Contract for Differences). The fact that in the end it is the end consumer who suffers is of no interest to high finance, the EU and US elites. Take Elon Musk, for example. Do you think he earns his money by selling electric cars? Not by any means. By 2021, he won’t have made a single cent of profit from car production. Until last year, his company made its best profits from trading CO2 certificates. In the last three years it was $3.3 billion. Another of Musk’s gold mines is trading in Bitcoin. As reported by Tagesschau at one time, Tesla had acquired Bitcoins for $1.5 billion from January to March 2021 and then resold them for the profit of $300 million. Everyone knows that Bitcoin production and transaction means enormous energy consumption. Never mind, the main thing is that it is a modern currency. Wow! Are electric cars not environmentally friendly at all because exorbitant amounts of precious and industrial metals are needed in their production? No problem. The main thing is to scrap old cars and buy new “emission-free” ones, according to the Green narrative. You have a Tesla? Wow! The ruble is rolling, one would like to say, although the ruble is just rolling towards China, as Russia has multiplied its exports to the Middle Kingdom since the sanctions were introduced, making nonsense of the West’s sanctions. Driving old diesel is yuck, but taking a tour into space with Spacex is mega cool. Isn’t that right, Greta? You’ve already circled the globe with the most environmentally unfriendly means of transport. The time is coming for the moon. Putin’s action against Ukraine is simply a good reason to speed up the green revolution in the West.  Continue reading